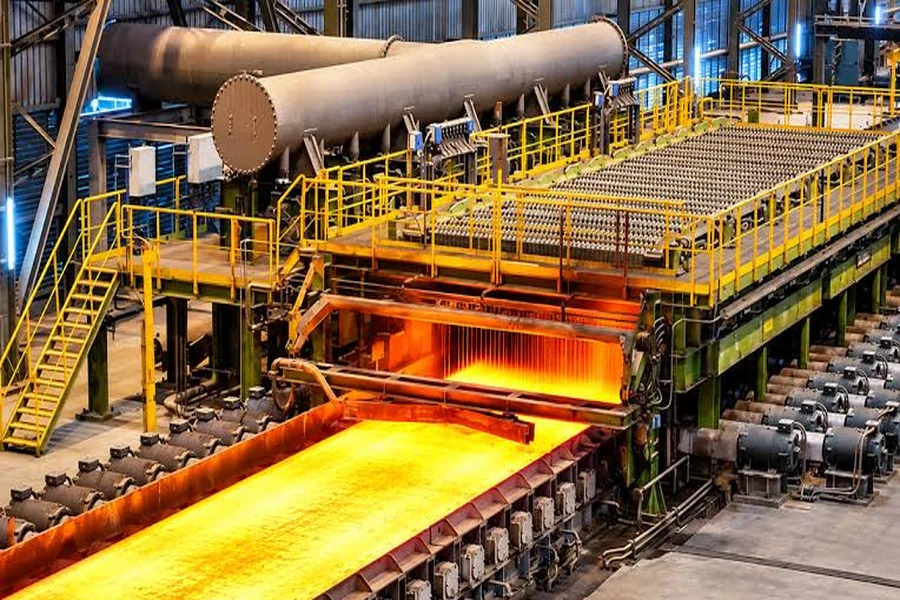
For a long time, refractory linings were treated as a background line item. Purchasing scheduled the order, the material showed up, the reline happened during the planned outage, and the furnace went back to work. The lead time was known, the price was steady, and the paperwork was boring.
That predictability has quietly slipped away. Specialty refractories and the raw materials behind them, including high-alumina bauxite, magnesia, graphite, and zirconia, are moving on longer, less certain lead times than they used to. Plants that once ordered a few weeks out are now planning a year or more in advance, and the ones that don’t are finding out the hard way that the outage schedule doesn’t wait for the brick.
The Shortage Isn’t Really About the Brick
The visible symptom is a longer quote from the refractory supplier. The actual problem sits several steps upstream, at the mine and the calcining kiln. Alumina prices moved sharply through 2024 and 2025 as bauxite supply, energy costs, and export policy all pushed in different directions at once. When any one of those inputs tightens, the finished refractory tightens with it, and the delay lands on the plant that ordered it.
The Outage Window Doesn’t Move
A furnace, kiln, or ladle reline is usually locked to a planned maintenance window that was scheduled months earlier. Crews are booked. The rest of the plant works around it. If the specialty brick or castable doesn’t arrive in time, the choices are all bad: extend the outage, install a lower-grade substitute, or run the vessel harder for another campaign and hope the lining holds.
None of those are free. A short substitute may cut the next campaign in half. A stretched outage cascades into every downstream schedule. As one industry overview puts it, stable production really does start with the refractory.
Sourcing Has Quietly Become a Design Decision
When lead times were short, the spec came first and sourcing followed. Engineering picked the ideal material for the service condition, and procurement went out and bought it. That order is reversing on a lot of jobs now. Availability is starting to shape the spec, not the other way around.
- Qualifying a second material. Plants are pre-qualifying a backup lining that uses a different raw material base, so a shortage in one input doesn’t stall the whole reline.
- Ordering earlier. Buyers are placing orders further ahead of the outage, and sometimes carrying inventory the plant used to refuse to hold.
- Widening the supplier bench. Single-source arrangements are being reworked so a second broker or manufacturer can step in without a fresh qualification cycle.
Many plants are absorbing this by working with a specialist broker that sources refractories and industrial raw materials across multiple mills and mines. The buyer isn’t chasing one datasheet anymore. They’re chasing whichever qualified equivalent can actually land on the loading dock in time.
Where This Goes From Here
Raw material supply for specialty refractories isn’t going back to what it was. Demand from steel, cement, glass, and petrochemical producers keeps pulling on the same limited pool of high-grade inputs, and the mines and processors behind them can’t scale overnight. The plants that adjust are the ones treating sourcing as part of production planning, with the same seriousness they give to labor, energy, and spare parts.
The lead time nobody used to budget for is now the lead time that decides whether the next campaign starts on schedule. That’s a planning problem, not a purchasing one, and the sooner it gets treated that way, the smaller the surprises get.
